
NatWest Group Halts United States and European Government Bond Dealing to Simplify Market Operations


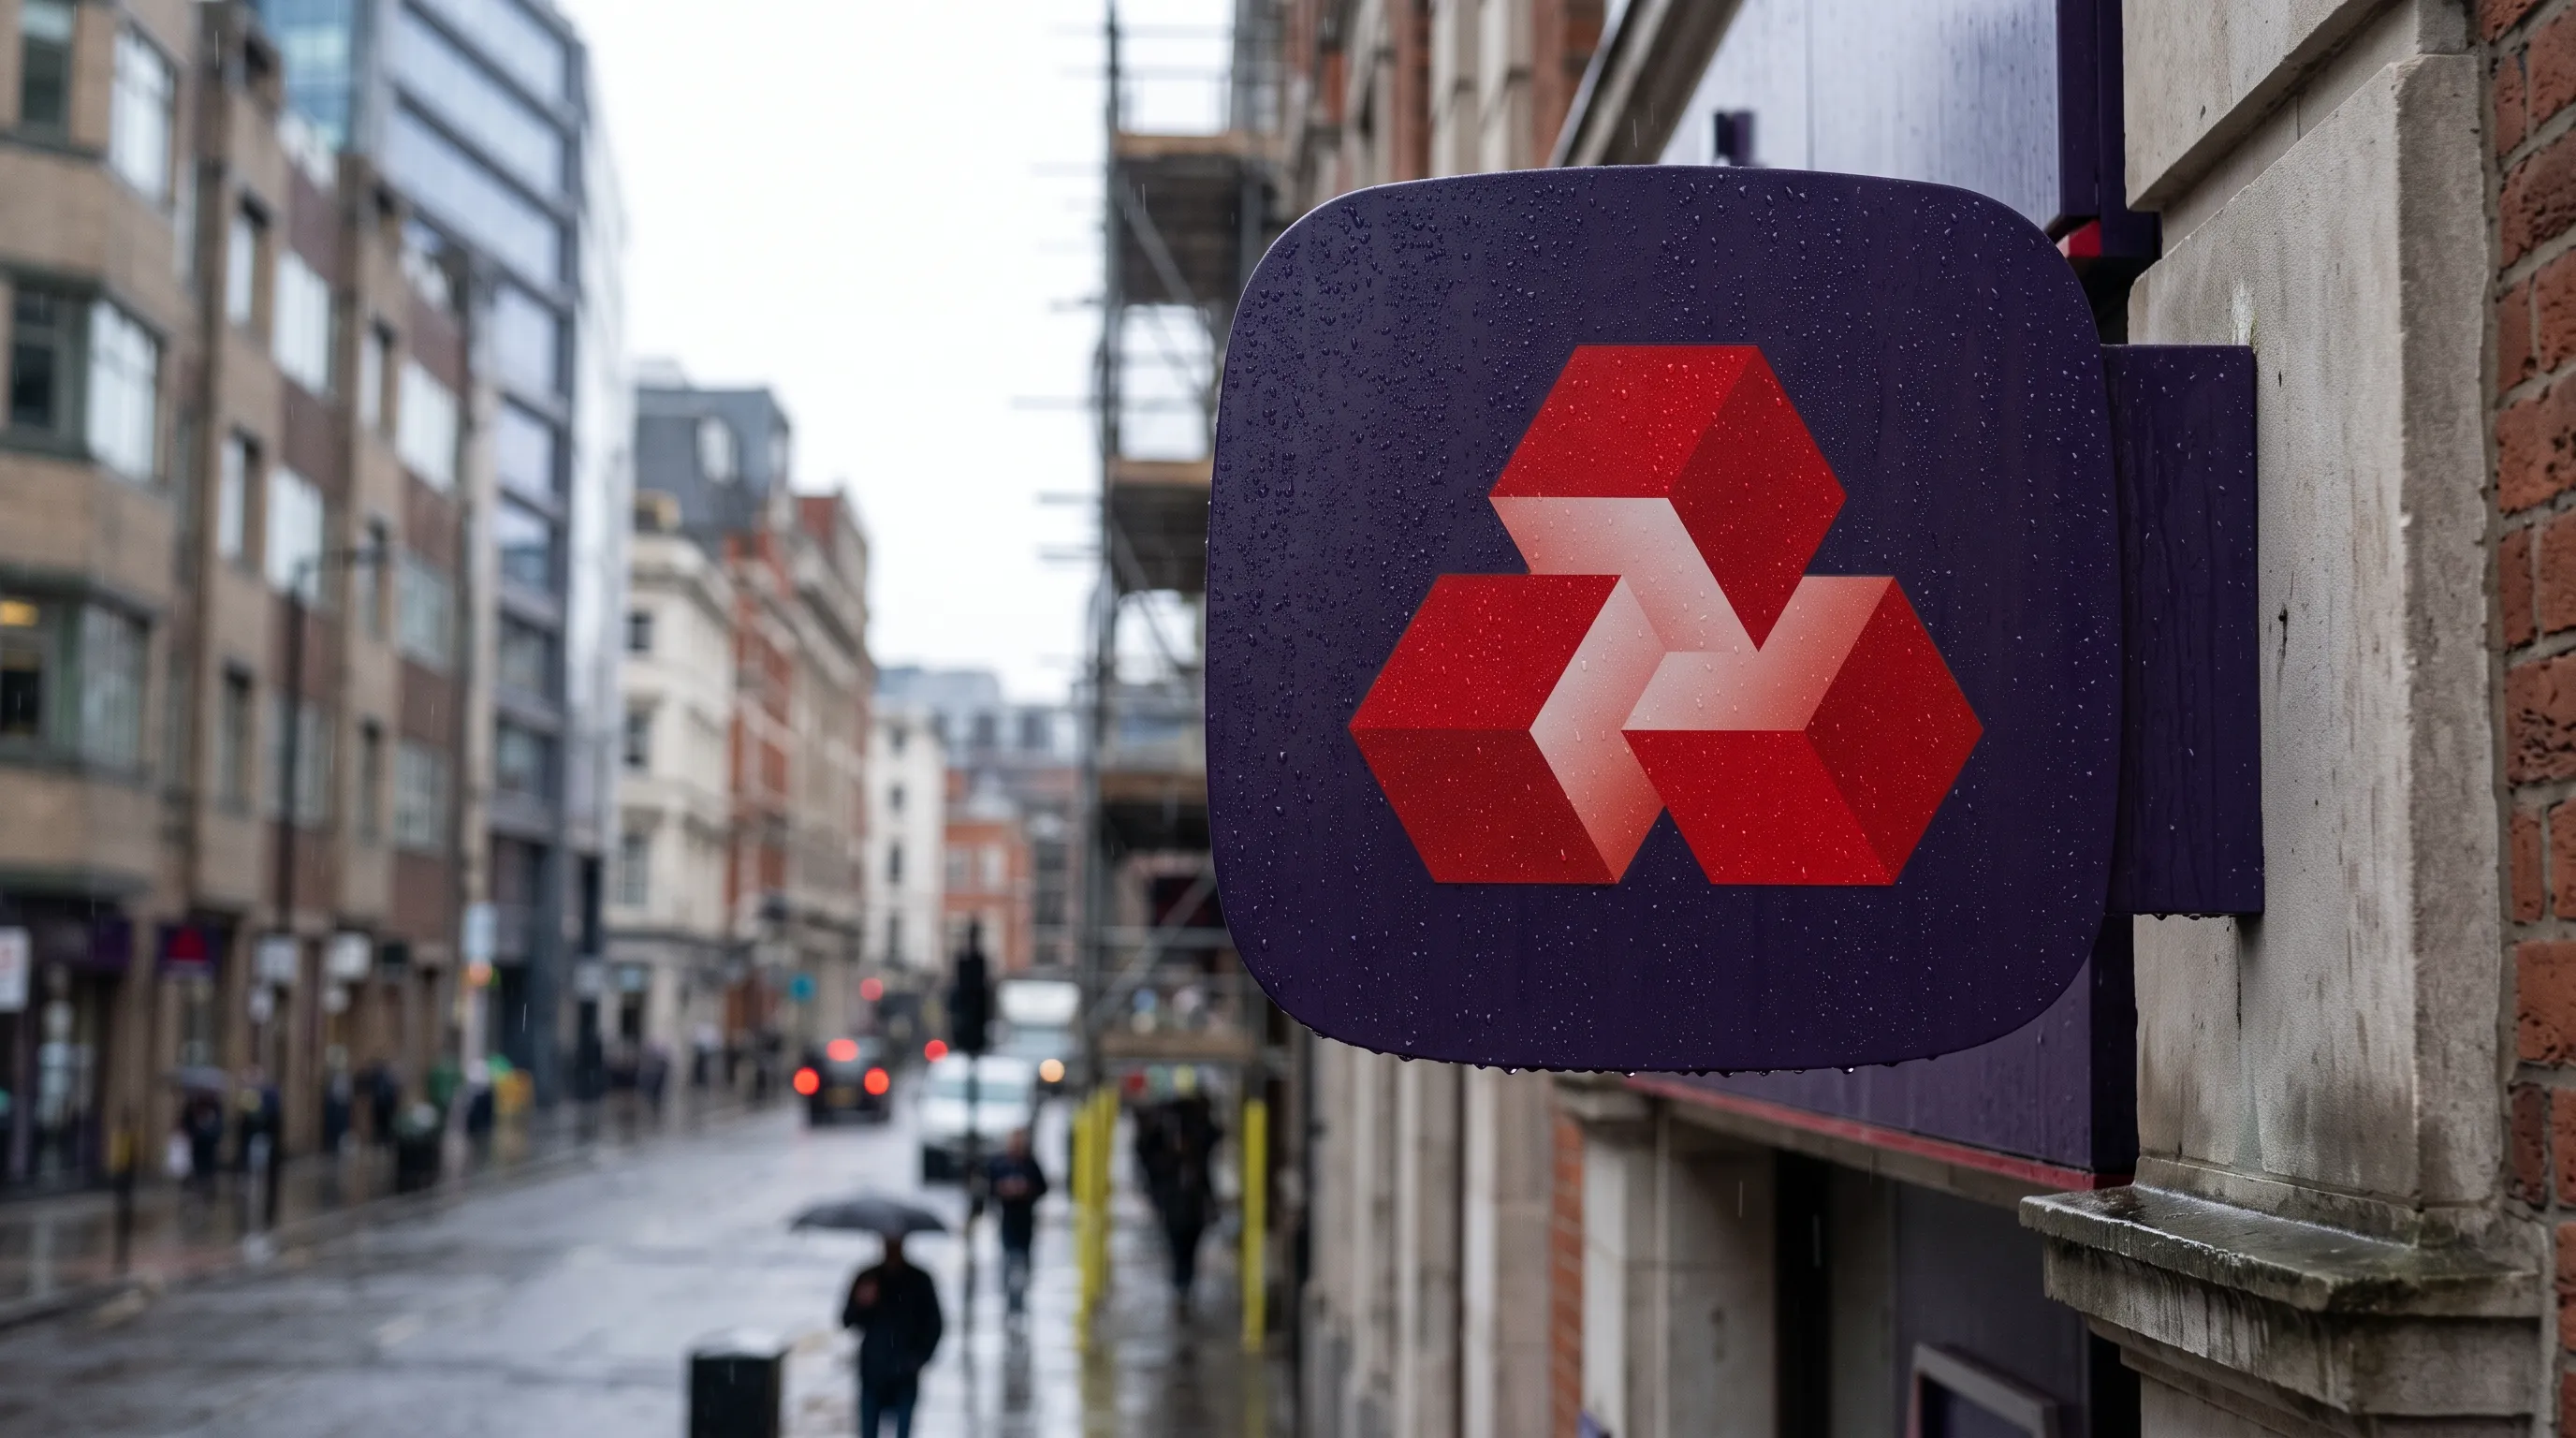
October 8, 2026 – NatWest Group is officially withdrawing from its primary dealership programs across the United States and European government bond markets.
The major British financial institution confirmed on Thursday that it intends to close its overseas government bond trading desks in a strategic effort to simplify its broader markets business structure.
For macroeconomic allocators, this withdrawal signals a deliberate shift away from balance-sheet-intensive trading operations that require institutions to hold massive temporary inventories of sovereign debt.
Trading desks observe that NatWest shares slipped approximately 1.1 percent in United States premarket trading following the announcement, reflecting broader market structural concerns regarding thinning institutional liquidity.
Strategic Restructuring and Job Reductions
A corporate spokesperson indicated that the proposed withdrawal will allow the enterprise to focus resources on areas with the strongest customer growth and demand.
Moving forward, the markets unit will pivot heavily toward financing, advisory services, currencies, and corporate debt capital markets.
Crucially, NatWest will maintain its status as a primary dealer within its domestic United Kingdom bond market, concentrating its sovereign debt operations entirely within its home jurisdiction.
Quantitative analysts note that closing the United States and European government bond desks will result in the loss of up to 10 trading and sales positions across the organization.
Corporate sources explicitly clarified that this strategic realignment was pre-planned and remains unrelated to the severe volatility recently observed across global fixed-income markets.
Market Plumbing and Liquidity Concerns
While NatWest’s exit primarily impacts its internal structure, the broader implications for sovereign debt market plumbing are drawing significant institutional attention.
Primary dealers are legally obligated to commit short-term funding to temporarily warehouse government bonds and provide continuous price quotes, particularly during periods of intense market stress.
As banks continue to decide that the underlying economics of this business are not worth the strict capital constraints, overall market liquidity can thin out significantly.
Asset managers project that fewer firms willing to rapidly absorb government debt could mechanically translate into wider bid-ask spreads and weaker demand during major Treasury auctions.
Fixed-income funds expect other mid-tier financial institutions to face similar pressure as they evaluate whether the costs of maintaining global primary dealership status justify the heavy capital encumbrance.
Read more
 Norway's 2 Trillion USD Sovereign Fund Proposes 80 Billion USD Cut to US Treasuries
September 4, 2026 – The manager of Norway’s massive sovereign wealth fund has formally proposed a historic structural shift to its fixed-income portfolio.Norges Bank Investment Management (NBIM) recommended slashing its global government bo…
Donia Saad•04 September Invesco Nasdaq Technology ETF Halts Trading at Market Open Amid Retail Speculation
August 27, 2026 – The Invesco Nasdaq Technology ETF triggered immediate retail speculation early Thursday morning following a sudden announcement that trading would be suspended at the market open.According to data provider Jin10 and confir…
Donia Saad•27 August Bitcoin Defends 78,000 USD as Treasury Bond Interventions Ignite a Massive Institutional Debasement Trade
August 26, 2026 – Bitcoin is consolidating near 78,768 USD during Wednesday trading, retaining the vast majority of its explosive 25% weekly surge that temporarily pushed the premier cryptocurrency above the 80,000 USD threshold.While retai…
Donia Saad•26 August Gold Surges Past $4,580 as U.S. Debt Benchmark and Treasury Buybacks Trigger Sovereign Hedge Surge
August 23, 2026 – Spot gold prices rallied aggressively over 1.5% during recent trading sessions to test the $4,603.92 mark, capping off a 5% weekly gain.The sharp upward momentum reflects a fundamental shift in investor behaviour as market…
Donia Saad•23 August Gold Spot Prices Near $4,346 as Rising Bond Yields Challenge Bullion Rally
August 19, 2026 – Spot gold prices pulled back slightly to trade near $4,346.13 per ounce during recent market sessions, as a sudden surge in global sovereign bond yields created a fresh macroeconomic drag on precious metals.The modest decl…
Donia Saad•19 August